
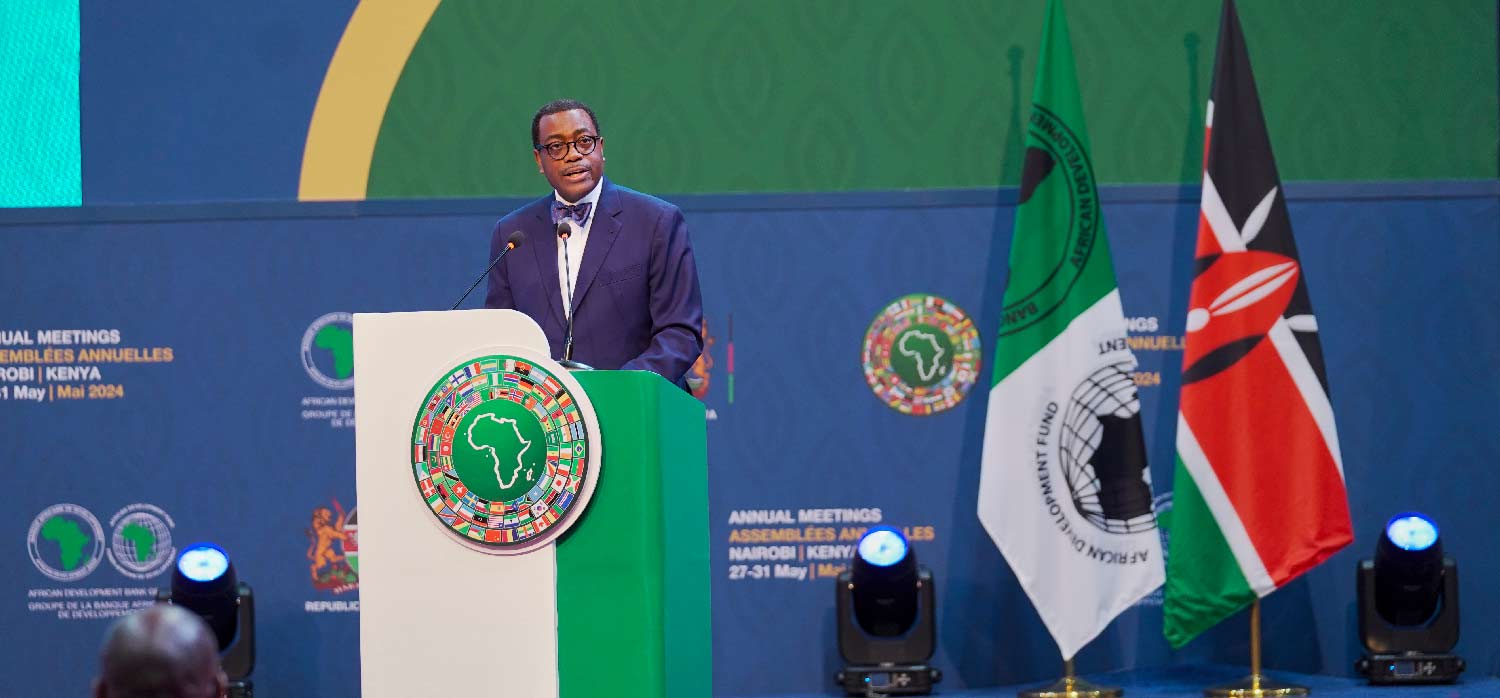
Kenya must bridge a projected \$12.5 billion (Sh1.6 trillion) financing gap—equivalent to 11.6 percent of its GDP—by 2030 to stay on track in achieving key Sustainable Development Goals (SDGs), according to the African Development Bank (AfDB). In its 2025 Country Focus Report, the bank stresses the urgency for Kenya to mobilise a wide range of capital sources over the next four years to meet development targets. The AfDB identifies pressing investment needs in sectors such as roads, education, energy, and research and development. Infrastructure, especially road development under SDG 9, represents the largest share of the required funding at 55 percent, followed by education (SDG 4) at 22 percent, energy access (SDG 7) at 20 percent, and innovation and research (also under SDG 9) at 9 percent.
The report underscores that these sectors are vital for fostering inclusive growth and reducing poverty. Without adequate investment and financing reforms, Kenya risks falling short of its 2030 SDG commitments. To close the funding gap, the AfDB calls for stronger public-private partnerships, improved fiscal strategies, and innovative financing approaches. The report emphasises that achieving Vision 2030 and the SDGs demands the strategic mobilisation of various forms of capital—including fiscal, natural, human, business, and financial resources. However, it notes that current capital utilisation is fragmented, and calls for better coordination between public and private sectors to ensure sustainable, inclusive progress.
Despite some gains, Kenya’s overall progress has slowed. The country dropped to 123rd out of 166 nations in the 2024 SDG Index, with a 62.1 percent overall achievement score, down from 118th out of 163 in the previous year. The AfDB partly attributes this decline to the non-inclusive nature of Kenya’s economic growth, noting that uneven development across sectors continues to hinder national advancement.